Credit Score Estimator: Know Your Score Before Lenders Do
Estimate your credit score in seconds without a credit check. Learn what really moves your score, the statement-date trick that can cut reported utilization tenfold, how long credit problems last, and what each score tier costs on a mortgage.
Sanjay Singh
Published on 14 Oct 2026 • Updated on 14 Oct 2026
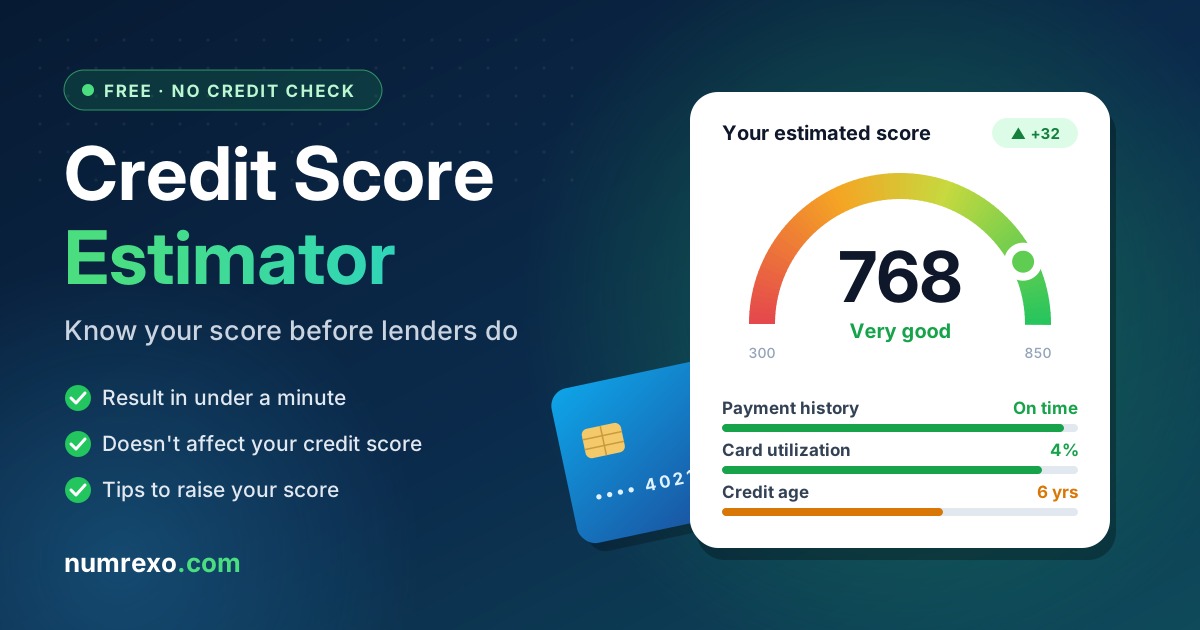
Two people take out the same $378,384 mortgage on the same day. One has a FICO Score of 780, the other 630. Over 30 years, the second person pays about $60,000 more in interest, for the same house and the same loan. Your credit score is one of the most expensive numbers in your financial life, yet most people only see it when a lender pulls it. A credit score estimator lets you see roughly where you stand first, so you can fix problems before they cost you. Quick answer: a credit score estimator asks a few questions about your credit habits, such as on-time payments, card balances, how long you have had credit and recent applications, and uses the published weight of each factor to estimate the range your score probably falls in. It does not pull your credit report, so it cannot affect your score. Answer the questions in the Credit Score Estimator on this page to see your estimated range in under a minute. This guide explains what the estimate means and how scores work in the US, India, the UK, Canada and Australia. It also covers four things most guides skip: the statement-date trick that can cut your reported utilization tenfold, the credit age maths of opening a new card, a recovery timeline for common credit problems, and what each score tier is worth in real money. What is a good credit score? A credit score is a number that predicts how likely you are to repay borrowed money on time. Lenders use it to decide whether to approve you and what interest rate to charge. Higher is better on every scale, but the scales differ by country and by agency. United States: FICO and VantageScore (300–850) Rating FICO Score VantageScore 3.0 Exceptional / Super prime 800–850 781–850 Very good / Prime 740–799 661–780 Good 670–739 (part of Prime) Fair / Near prime 580–669 601–660 Poor / Subprime 300–579 300–600 The average US FICO Score was 714 in FICO's Spring 2026 report, down two points in a year as student loan delinquencies returned to credit reports. Other countries at a glance Country Main agencies Scale Generally considered good India TransUnion CIBIL, Experian, Equifax, CRIF High Mark 300–900 700+ (750+ for the best loan offers) United Kingdom Experian 0–1,250 861+ United Kingdom Equifax 0–1,000 531+ United Kingdom TransUnion 0–999 (new scale) 653+ Canada Equifax, TransUnion 300–900 660+ (Equifax) Australia Equifax 0–1,200 622+ Australia Experian
0–1,000 625+ https://numrexo.com/finance/home-loan-eligibility-calculator https://numrexo.com/finance/car-loan-emi-calculator https://numrexo.com/finance/personal-loan-emi-calculator https://numrexo.com/finance/loan-eligibility-calculator
The numbers look very different, but the idea is the same everywhere: on most scales, "good" starts somewhere between half and two thirds of the way up. A 700 means very different things in London and in Mumbai, so always read a score against its own scale. Recent changes worth knowing: Experian UK moved from a 999 to a 1,250 scale in late 2025. TransUnion UK is moving from 710 to 999, rolling out from September 2026 to June 2027, so you may see two different TransUnion scores for a while. In India, lenders have had to report credit data to bureaus every 15 days instead of monthly since January 2025, so changes show up faster. The five factors behind your score Every major scoring model looks at the same five areas of your credit report. FICO publishes how much each one matters for the general population, and that is the backbone of any good credit score estimator.
- Payment history (35%). Whether you pay on time, how late any missed payments were, and how recently they happened. In the US, a payment is generally not reported as late until it is a full 30 days past due, so a payment that is a few days late usually costs you a fee, not points.
- Amounts owed (30%). Mostly your credit utilization: card balances divided by card limits. A $1,500 balance on $5,000 of limits is 30% utilization. Lower is better, and both your overall utilization and each card's utilization count.
- Length of credit history (15%). The age of your oldest account, your newest account, and the average age of all of them.
- New credit (10%). Recent applications (hard inquiries) and newly opened accounts. Several new accounts in a short time look riskier.
- Credit mix (10%). Having different types of credit, such as cards and instalment loans, helps a little. It is never worth taking a loan just to improve your mix.
VantageScore and the scores used in India, the UK, Canada and Australia use the same building blocks with their own weights, which they do not publish in the same detail. That is why an estimator gives you a range, not an exact number. How a credit score estimator turns your answers into a number A well-built estimator works like this:
- It asks one or two questions for each factor, for example "Have you missed a payment in the last two years?" or "Roughly what share of your card limits are you using?"
- It scores each answer within its factor, from weakest to strongest.
- It combines the factor scores using weights similar to the ones above.
- It maps the result onto the score scale and shows the band you most likely fall in. Because the real models use hundreds of data points from your actual report, treat the result as a direction-finder. If the estimate and your real score are far apart, your report probably contains something you were not aware of, which is worth checking. The statement-date trick: same spending, 10× lower utilization Here is something that surprises even people who pay their card in full every month: your score does not see what you pay. It sees the balance on the day your card reports to the bureau. For most US card issuers, that is your statement closing date, not your payment due date. Imagine you spend $2,000 a month on a card with a $5,000 limit and always pay the full bill on time.
When you pay Balance reported Utilization the score sees Interest paid On the due date, after the statement closes $2,000 40% $0 On day 27, a few days before the statement closes $200 4% $0 You spend the same, pay the same and pay no interest in either case. But in the first case your report shows a card that is 40% used. In the second it shows 4%. How to use it
- Find your statement closing date in your card app or on your last statement.
- Two or three days before it, pay most of the balance.
- Pay whatever is left on the due date as usual. This matters most in the month or two before you apply for a mortgage, car loan or new card. Widely used models such as FICO Score 8 judge utilization on the balances currently reported, so the improvement can show up as soon as the next statement is reported. Newer "trended data" models also look at how your balances moved over recent months, which is one more reason to keep balances low as a habit, not just before an application. Good to know: some issuers report on other dates, such as the last day of the month. If your utilization does not drop after trying this, ask your card issuer when it reports. In India, banks now send updates to the bureaus at least every 15 days, so the timing works differently; there, keeping the balance low throughout the month is the safer approach. Credit age maths: what one new card really does Opening a new account lowers the average age of your accounts. How much depends on how many accounts you already have, and the difference is bigger than most people expect. Say your existing accounts average 6 years old. Here is your new average the day a brand-new card appears: Existing accounts Average age before Average age after one new card Drop 1 6.0 years 3.0 years −50% 2 6.0 years 4.0 years −33% 3 6.0 years 4.5 years −25% 5 6.0 years 5.0 years −17% 10 6.0 years 5.5 years −9% The formula is simple: new average = (old average × number of accounts) ÷ (number of accounts + 1). What this tells you • Thin files feel new accounts most. If you have only one or two accounts, a new card halves or nearly halves your average age. • Space out applications. Each new account also adds a hard inquiry, so two cards in two months hit both "new credit" and "length of history" at once. • Keep your oldest card open. Closing an old, fee-free card can shorten your history over time and also cuts your total limit, which raises utilization. If it has an annual fee, ask the issuer about switching to a no-fee version instead of closing it. • Time heals this one. Your average age rises again every year you wait, and a new account soon becomes an old one. How long credit problems follow you Not every problem on your report is equal. Some fix themselves next month; others stay for years. Knowing which is which tells you where to put your effort.
Item (US) How long it can stay What you can do High card balance Until the next balance is reported (about a month) Pay it down before the statement closes Hard inquiry Up to 2 years on the report; FICO Scores count it for 12 months Apply only when you need credit; rate-shop within a short window Late payment (30+ days) Up to 7 years Get current fast and stay current; its effect fades as it ages Collection or charge-off Generally up to 7 years Check it is accurate; dispute errors with the bureau Bankruptcy Up to 10 years Rebuild with on-time payments and low balances These reporting limits come from US law and the CFPB. The time limits do not apply when a report is used for a job paying more than $75,000 a year, or for credit or life insurance of more than $150,000. Shopping for a loan without hurting your score For mortgages, car loans and student loans, FICO treats several applications in a short window as one inquiry. Newer FICO versions use a 45-day window and older versions 14 days, and inquiries less than 30 days old are ignored. Credit card applications do not get this treatment. To be safe with any lender, do your rate shopping within two weeks. What fades and what doesn't The older a negative item gets, the less it weighs. A single 30-day late payment from five years ago hurts far less than one from last month, as long as everything since has been on time. That is why the most powerful thing you can do after a mistake is simple: never miss another payment. What your credit score is worth in real money A credit score feels abstract until you put a price on it. Here is what different FICO tiers meant for a typical US mortgage in 2026: a $378,384 loan (the average new purchase loan in April 2026) on a 30-year fixed rate.
FICO Score APR Monthly payment Total interest over 30 years Extra vs top tier 760–850 6.70% $2,442 $500,602 — 700–759 6.95% $2,505 $523,310 +$22,707 680–699 7.07% $2,535 $534,292 +$33,690 660–679 7.11% $2,545 $537,965 +$37,362 640–659 7.21% $2,571 $547,172 +$46,569 620–639 7.36% $2,610 $561,049 +$60,447 APRs by tier are myFICO figures from May 2026; the payments and interest are calculated with the standard loan formula. Your own rate will differ. Your score, priced per point Moving from the middle of the lowest tier shown (about 630) to the middle of the top tier (about 805) is roughly 175 points, and it is worth about $60,447 on this loan. That works out to around $345 of interest per credit score point. Seen that way, raising your score by 40 points before you apply is worth roughly $13,800 over the life of this loan. The same logic applies to car loans, personal loans and credit cards, and in the US credit information can also affect insurance pricing and rental applications. If you are planning a home purchase, pair this estimator with our Home Loan Eligibility Calculator and Amortization Calculator to see the full picture. How to use the Credit Score Estimator
- Choose your country or score scale if the estimator asks, so the result is shown on the right range.
- Answer the payment questions honestly. Include any payment that was 30 or more days late, even if you have since caught up.
- Add up your card balances and limits. Use the balances on your latest statements, not today's balance after payments.
- Enter your credit history details: roughly how old your oldest account is and how many accounts you have.
- Count recent applications for cards and loans in the last 12 months.
- Read your estimated range and the factor that pulls your estimate down the most. How to read the result Estimated range (FICO-style scale) What it usually means Your next move 800–850 Best rates and approvals with most lenders Keep doing what you are doing 740–799 Very strong; close to top pricing Small utilization cuts may push you into the top tier 670–739 Good; approved by most lenders, but not at the best rate Focus on utilization and avoid new applications 580–669 Fair; fewer options and higher rates Fix late payments and pay down balances first 300–579 Poor; approvals are difficult Check your report for errors and rebuild with on-time payments Then check the real thing. In the US you can get free credit reports from all three bureaus at AnnualCreditReport.com, the official site. In India you are entitled to one free full credit report a year from each credit bureau, and many apps show your score for free. Checking your own report or score is a soft inquiry and does not lower it. If the estimate and your real score are far apart, look for an account you do not recognise, a late payment you believe is wrong, or a balance reported higher than it is. Errors can be disputed directly with the bureau. A 90-day plan to raise your score No one can promise a specific number of points, and anyone who does is guessing. But these steps target the factors that respond fastest. Days 1–30: find and stop the damage • Get your credit reports and check every account, balance and late payment. • Dispute anything that is wrong with the bureau that reports it. • Set up automatic minimum payments on every account so nothing is ever 30 days late again. • Note each card's statement closing date. Days 31–60: cut reported utilization • Pay balances down before each statement closes, starting with the card that is most used as a share of its limit. • Aim to keep overall utilization well below 30%; lower is better. • If you have a card in good standing, ask for a credit limit increase, but only if the issuer can do it without a hard inquiry. • Do not open or close any accounts. Days 61–90: protect the gains • Keep balances low through two more statement cycles. • Avoid new credit applications unless you need them. • Run the Credit Score Estimator again and compare it with your real score. • If you plan to apply for a mortgage or car loan, do all your rate shopping within two weeks. Utilization changes can show up within one or two statement cycles. Late payments, collections and a short history take longer, so the sooner you start, the better. Credit score myths that cost people money Myth Reality Checking my own score lowers it Checking your own score or report is a soft inquiry and has no effect. Carrying a small balance builds credit Paying in full builds credit just as well and costs no interest. Paying in full means my utilization is zero Your score usually sees the statement balance, even if you pay it in full afterwards. Closing old cards helps my score It can raise utilization and, over time, shorten your history. My income affects my score Income is not part of your credit score, though lenders check it separately. I have one credit score You have many: different bureaus, models and versions can each give a different number. A debit card builds credit Debit card use is not reported to credit bureaus. Frequently asked questions How accurate is a credit score estimator? It gives a realistic range, not your exact score. Real scores use hundreds of details from your credit report, and each bureau and model can give a different number. Use the estimate to see where you stand and which factor to work on. Does using a credit score estimator affect my credit score? No. An estimator only uses the answers you type in and never pulls your credit report, so there is no inquiry of any kind. What is a good credit score? On the US FICO scale of 300 to 850, 670 to 739 is good, 740 to 799 is very good and 800 or more is exceptional. In India, a CIBIL score of 700 or more is generally good, and 750 or more gets the best loan offers. What is the fastest way to raise my credit score? Lowering the card balances that are reported to the bureaus usually works fastest, often within one or two statement cycles. Paying down balances before your statement closing date helps the most. Why are my scores different on different apps? Each app may show a score from a different bureau, a different scoring model (such as FICO or VantageScore) or a different version, and each is based on data reported at a different time. Does my salary affect my credit score? No. Income is not part of your credit score. Lenders look at your income separately when deciding how much to lend you. How long does a late payment stay on my credit report? In the US, a payment 30 or more days late can stay on your report for up to seven years, but its effect on your score shrinks as it gets older and you keep paying on time. How often does my credit score change? Whenever new information is reported. Most US card issuers report once a month, around your statement date. In India, lenders must update credit bureaus at least every 15 days. Final thoughts Your credit score is built from a handful of habits: paying on time, keeping balances low, letting your accounts age and applying for credit only when you need it. An estimate shows you which of those habits needs attention, before a lender's decision does it for you. Run the Credit Score Estimator on this page, note the factor holding you back, and start with the statement-date trick this month. It costs nothing and can change what lenders see within weeks. Disclaimer: This article and estimator are for general information only and are not financial or credit advice. The estimate is not your actual credit score and is not provided by FICO, VantageScore or any credit bureau. Lenders use different scoring models and their own criteria. Rates and figures quoted are examples from the sources named and will change. Check your official credit reports and speak to a qualified adviser before making financial decisions.
Frequently Asked Questions
How accurate is a credit score estimator?▾
It gives a realistic range, not your exact score. Real scores use hundreds of details from your credit report, and each bureau and model can give a different number. Use the estimate to see where you stand and which factor to work on.
Does using a credit score estimator affect my credit score?▾
No. An estimator only uses the answers you type in and never pulls your credit report, so there is no inquiry of any kind.
What is a good credit score?▾
On the US FICO scale of 300 to 850, 670 to 739 is good, 740 to 799 is very good and 800 or more is exceptional. In India, a CIBIL score of 700 or more is generally good, and 750 or more gets the best loan offers.
What is the fastest way to raise my credit score?▾
Lowering the card balances that are reported to the bureaus usually works fastest, often within one or two statement cycles. Paying down balances before your statement closing date helps the most.
How often does my credit score change?▾
Whenever new information is reported. Most US card issuers report once a month, around your statement date. In India, lenders must update credit bureaus at least every 15 days.
What is a credit score estimator?▾
A credit score estimator is a free tool that predicts the range your credit score probably falls in, based on answers about your payment history, card balances, credit age and recent applications. It does not access your credit report.
What information do I need to use a credit score estimator?▾
You only need rough details: whether you have missed any payments, your card balances and limits, how long you have had credit, how many accounts you have, and how many times you applied for credit in the last 12 months.
Why are my scores different on different apps?▾
Each app may show a score from a different bureau, a different scoring model (such as FICO or VantageScore) or a different version, and each is based on data reported at a different time.
Does my salary affect my credit score?▾
No. Income is not part of your credit score. Lenders look at your income separately when deciding how much to lend you.
How long does a late payment stay on my credit report?▾
In the US, a payment 30 or more days late can stay on your report for up to seven years, but its effect on your score shrinks as it gets older and you keep paying on time.
What is the difference between FICO and VantageScore?▾
Both are credit scoring models that usually run from 300 to 850 and look at the same kinds of information. FICO is made by the Fair Isaac Corporation, while VantageScore was created by the three major US credit bureaus. They weigh factors differently, so your two scores can differ.
What is credit utilization?▾
Credit utilization is the share of your credit card limits you are using. For example, a $1,500 balance on $5,000 of total limits is 30% utilization. Keeping it well below 30% is generally better for your score.
If I pay my credit card in full, is my utilization zero?▾
Not always. Most card issuers report your statement balance to the bureaus, so your score may see a high balance even if you pay it in full later. Paying before the statement closing date lowers the balance that gets reported.
Will closing an old credit card hurt my credit score?▾
It can. Closing a card reduces your total credit limit, which can raise your utilization, and over time it can shorten your credit history. If the card has no annual fee, keeping it open is usually better.
How much does a hard inquiry lower my credit score?▾
For most people, one additional hard inquiry lowers a FICO Score by less than five points. Several applications in a short time can have a bigger combined effect.
How long do hard inquiries stay on my credit report?▾
Hard inquiries can stay on your credit report for up to two years, but FICO Scores only count them for the first 12 months.
Can I compare mortgage rates without hurting my credit score?▾
Yes. FICO treats several mortgage, auto or student loan inquiries within a short window as a single inquiry: 45 days in newer versions and 14 days in older ones. To be safe, do all your rate shopping within two weeks.
What is the average credit score in the US?▾
The average US FICO Score was 714 in FICO's Spring 2026 report, down two points from a year earlier.
What is a good CIBIL score in India?▾
CIBIL scores range from 300 to 900. A score of 700 to 749 is generally considered good, and 750 or above is considered excellent and gives you the best chance of loan approval at good rates.
How can I check my real credit score for free?▾
In the US, you can get free credit reports from all three bureaus at AnnualCreditReport.com, and many banks and apps show a free score. In India, you can get one free full credit report a year from each credit bureau. Checking your own report or score does not lower it.
Get new calculators & guides by email
Occasional updates when we add a new calculator or publish a useful guide. No spam, unsubscribe anytime.
By subscribing you agree to our Privacy Policy.